
Updated September 2026. Most homebuyers treat prequalification and preapproval as interchangeable terms. They are not — and choosing the wrong one at the wrong time can cost you real money before you have toured a single home.
Here is what most lenders will not tell you upfront: a standard preapproval triggers a hard credit inquiry that can drop your score 5–10 points and remain on your report for two years, according to the Consumer Financial Protection Bureau. That matters when a single credit-tier difference changes your interest rate and — by extension — your total loan cost over 30 years. For a buyer with a $300,000 FHA loan, a tier drop from 590 to 580 caused by an unnecessary hard pull can add over $16,000 in interest across a 30-year term — a real dollar cost for simply asking questions.
This guide breaks down exactly what each step does, when to use it, and which options let you get pre-qualified without touching your credit score at all — including the NoTouch Credit Pull, FreePreQuals.com’s proprietary soft pull mortgage pre-qualification process that delivers a real pre-qualification letter at zero cost and zero credit score impact. The NoTouch Credit Pull is the only true no hard inquiry mortgage pre-qualification on this list, and it is the recommended first step for every buyer in Virginia, Florida, Tennessee, and Georgia who is still in the exploration phase.
By Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC, NMLS #376205 | Licensed in Virginia, Florida, Tennessee, and Georgia
We have ranked the options starting with the only broker in this space offering a genuine free soft pull pre-qualification at no cost — so you can see exactly how the no hard inquiry mortgage pre-approval model and the broader mortgage pre-approval without hard pull approach stack up against the rest of the industry before you commit to anyone. Use Duane’s mortgage pre-qualification tool to model your own scenario based on your actual numbers before a single hard pull ever touches your credit file. Buyers in Virginia, Florida, Tennessee, and Georgia can start today at zero cost and zero credit score impact — protecting the score that determines your rate from the very first step.
Prequalification vs. Preapproval: The Core Difference
Prequalification is an estimate. You provide basic financial information, a lender reviews it, and you receive a general sense of what you might qualify for. Done correctly, it uses a soft pull that leaves your credit score untouched.
Preapproval is a verified commitment. The lender pulls your full credit report, verifies income, assets, and employment, and issues a letter stating you are approved up to a specific loan amount. This process requires a hard inquiry, which does impact your score.
The strategic question isn’t which one is “better” in isolation. It’s about sequencing. Early-stage buyers exploring their options have no reason to absorb a hard pull before they’ve even found a home. That’s where a soft pull mortgage pre-qualification becomes a genuinely useful tool, not just a marketing term.
The credit score cost in real dollars: Consider a borrower applying for a $300,000 FHA loan. FICO score tiers affect the interest rate a borrower qualifies for. If an unnecessary hard pull drops a score from 590 to 580, that borrower may slip into a lower pricing tier. On a 30-year loan, even a 0.25% rate difference adds up to roughly $15,000 in additional interest over the life of the loan. That is the real cost of a premature hard pull. Use Duane’s mortgage pre-qualification tool to model your own scenario based on your actual numbers.
By Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC, NMLS #376205
Here are the top options for getting pre-qualified or preapproved in 2026, ranked by their approach to credit impact.
1. FreePreQuals.com — NoTouch Credit Pull Pre-Qualification
Best for: Buyers who want to know their budget before committing to any lender, without credit score risk.
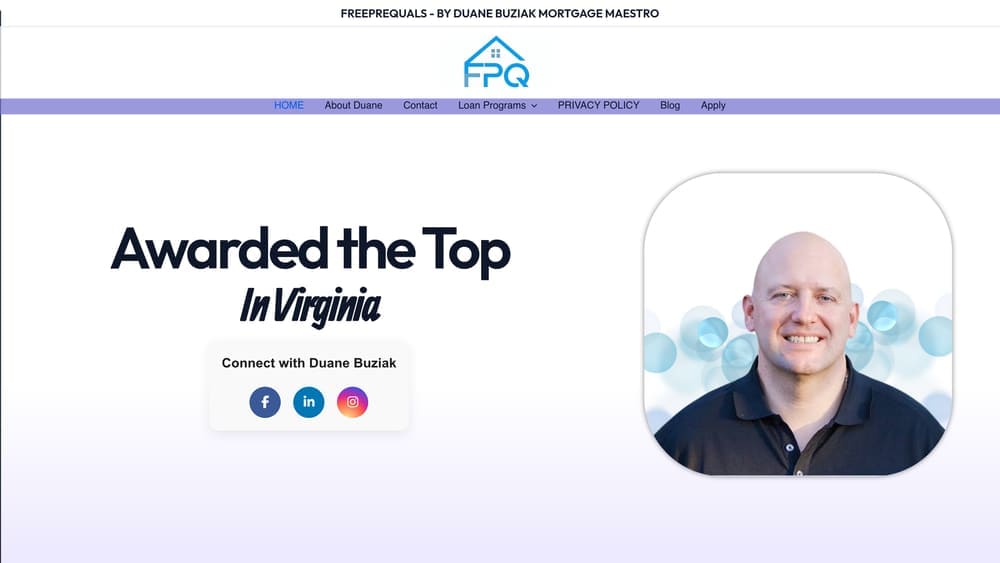
FreePreQuals.com is the only option on this list that pre-qualifies borrowers using a soft pull only, with zero credit score impact and no cost to the borrower.
Where This Tool Shines
The fundamental problem with most preapproval processes is that they require you to absorb a credit hit before you’ve even decided on a lender. FreePreQuals.com solves this directly. Duane Buziak, operating as a broker under Coast2Coast Mortgage LLC (NMLS #376205), uses a NoTouch Credit Pull to generate a genuine pre-qualification letter, not a vague estimate, but a real document you can use while shopping.
What separates this from a generic “soft pull check” is that Duane is an actual broker with access to over 500 wholesale lenders. You’re not filling out a form that routes to a call center. You’re working directly with a Virginia Broker of the Year (2024–2025) and Scotsman Guide Top Originator recognized in both 2025 (#114, $44.4M) and 2026 ($51.2M), with 1,400+ five-star reviews behind him. The pre-qualification is free. The expertise is real.
Key Features
NoTouch Credit Pull: Soft pull only, zero credit score impact, zero risk to your current credit tier.
Free Pre-Qualification Letter: A real pre-qual letter with no obligation, usable while you shop homes and compare programs.
Broker Access to Multiple Loan Programs: FHA, VA, USDA, Conventional, and Jumbo loans, including options up to the 2026 conforming limit of $806,500 (or $1,249,125 in high-cost areas).
Multi-State Licensing: Licensed in Virginia, Florida, Tennessee, Georgia, and Washington DC, with state-specific program knowledge in each market.
No-Out-of-Pocket Closing Options: Available on qualifying loans for borrowers who want to minimize upfront cash requirements at closing.
Best For
Early-stage homebuyers who want to understand their purchasing power before committing to a lender. Also ideal for credit-conscious borrowers, first-time buyers, veterans exploring VA loan eligibility, and self-employed borrowers who want a pre-qual without triggering a hard pull during the exploratory phase.
Pricing
Free. There is no cost for the pre-qualification. Standard broker fees and lender fees apply if and when you proceed to a full loan application.
2. Rocket Mortgage
Best for: Borrowers who are ready to commit to the preapproval stage and prefer a fully digital, self-service experience.
Rocket Mortgage is a major national digital lender known for its streamlined online application and fast preapproval turnaround.
Where This Tool Shines
Rocket’s primary strength is its digital infrastructure. The application process is designed to be completed entirely online, with document uploads, income verification, and preapproval letters all handled through their platform. For borrowers who are already confident in their credit profile and ready to move to a verified preapproval, Rocket’s speed and brand reliability make it a recognized choice.
The important caveat: Rocket’s standard preapproval process requires a hard credit inquiry. That means your score takes a hit the moment you apply. For buyers still in the exploration phase, this is a meaningful downside. The no hard inquiry mortgage pre-approval model that FreePreQuals.com offers is not part of Rocket’s standard process.
Key Features
Fully Digital Application: End-to-end online process from application to preapproval letter.
Fast Preapproval Turnaround: Designed for speed, with quick document processing through their platform.
Wide Loan Product Range: Conventional, FHA, VA, and jumbo loan options available.
Strong Customer Support Infrastructure: Large-scale support team and digital resources for borrowers.
Hard Pull Required: Standard preapproval triggers a hard credit inquiry, which will impact your credit score.
Best For
Borrowers who have already done their research, know their credit standing, and are ready to move into a verified preapproval. Not recommended for buyers still in the early exploration phase who want to protect their credit score.
Pricing
No upfront cost for the preapproval application. Standard lender fees apply at closing.
3. Guild Mortgage
Best for: Borrowers with complex loan scenarios who want in-person support alongside digital tools.
Guild Mortgage is a full-service mortgage lender with an extensive physical branch network and a reputation for handling diverse borrower profiles.
Where This Tool Shines
Guild’s differentiator is its branch presence. For borrowers who feel more comfortable sitting across from a loan officer, reviewing documents in person, or navigating a complex file, Guild’s branch network provides that option. They are known for working with borrowers who have non-standard income situations or loan types that require more hands-on guidance.
That said, Guild’s preapproval process follows industry-standard practice: a hard credit inquiry is required. Borrowers who are exploring mortgage pre-approval without hard pull options will not find that here. Guild is best suited for the stage when a borrower is ready to move forward with full documentation and a verified preapproval.
Key Features
Extensive Branch Network: Physical locations across many states for in-person borrower support.
Diverse Loan Programs: FHA, VA, USDA, conventional, and specialty loan options.
Dedicated Loan Officers: Assigned loan officers for complex borrower profiles and personalized guidance.
Hybrid Digital and In-Person Experience: Online tools available alongside branch access.
Hard Pull Standard: Preapproval requires a hard credit inquiry with associated credit score impact.
Best For
Borrowers with complex files, non-traditional income, or those who strongly prefer in-person guidance from a dedicated loan officer. Best engaged after initial soft pull pre-qualification has been completed.
4. Movement Mortgage
Best for: Buyers in competitive markets who need a verified preapproval on a tight timeline.
Movement Mortgage is known for its speed-focused underwriting model, designed to move borrowers through the process quickly in fast-moving real estate markets.
Where This Tool Shines
Movement’s positioning centers on turnaround speed. Their underwriting model is built to process applications faster than the typical lender timeline, which matters when a seller is reviewing multiple offers and a verified preapproval letter carries weight. Movement also operates with a local loan officer network, giving borrowers a regional point of contact rather than a purely centralized process.
The tradeoff is the same as the rest of the industry: Movement’s preapproval runs a hard pull. For buyers who haven’t yet completed a no credit impact mortgage pre-qual to understand their starting position, jumping straight to a Movement preapproval means absorbing a credit hit without a baseline understanding of where your score stands.
Key Features
Speed-Focused Underwriting: Designed for fast processing, useful in competitive offer situations.
Local Loan Officer Network: Regional officers provide community-level support alongside the digital process.
Multiple Loan Programs: FHA, VA, conventional, and other loan types available.
Mission-Driven Brand: Community-oriented positioning that resonates with many borrowers.
Best For
Active homebuyers in competitive markets who have already done their pre-qualification homework and need a fast, verified preapproval letter to support an offer.
5. Alcova Mortgage
Best for: Borrowers in the Southeast and Mid-Atlantic who prefer a relationship-oriented, regional lender over a large national brand.
Alcova Mortgage is a regional lender with a community-first service model, particularly strong in markets across the Southeast and Mid-Atlantic.
Where This Tool Shines
Alcova’s appeal is its size and approach. Borrowers who feel lost in the scale of a national lender often find that a regional lender like Alcova offers more personalized service, more accessible loan officers, and a greater sense of accountability. Alcova has built its reputation on relationship-oriented lending, where the loan officer you speak to at the start of the process is likely the same person guiding you through closing.
Like the other lenders on this list, Alcova’s preapproval process uses a hard pull as the industry standard. Borrowers in Virginia or the broader Mid-Atlantic region who want to explore their options first without credit impact should consider starting with a soft pull mortgage pre-qualification through FreePreQuals.com before engaging Alcova for a verified preapproval.
Key Features
Regional Community Focus: Service model built around personalized, relationship-oriented lending.
Personalized Loan Officer Relationships: Consistent point of contact throughout the process.
Broad Loan Program Access: FHA, VA, conventional, and other programs available.
Southeast and Mid-Atlantic Presence: Strong regional knowledge and market familiarity.
Best For
Borrowers in the Southeast and Mid-Atlantic who value a smaller, relationship-driven lender and are ready for a full preapproval with documentation.
6. NFM Lending
Best for: Borrowers with specialty financing needs, including VA loans, jumbo, FHA, and renovation loan programs.
NFM Lending offers a broad menu of loan programs and is licensed across many states, making it a solid option for borrowers whose needs go beyond a standard conventional loan.
Where This Tool Shines
NFM’s strength is program breadth. Borrowers with specialty needs, whether that’s a VA loan, a jumbo loan above the 2026 conforming limit of $806,500, an FHA loan, or a renovation financing scenario, will find NFM has dedicated program knowledge in each of these areas. Their loan officers tend to specialize, which can make a meaningful difference when a borrower’s file is more complex than a standard W-2 purchase.
The credit pull dynamic remains consistent with the rest of the industry: NFM’s preapproval process requires a hard inquiry. Borrowers who want to explore specialty program eligibility without a credit score impact should start with a NoTouch Credit Pull pre-qualification to establish a baseline before committing to a full NFM application.
Key Features
Broad Loan Program Menu: VA, FHA, conventional, jumbo, and renovation loan options available.
Wide Geographic Licensing: Licensed in many states with broad market reach.
Specialty Program Knowledge: Loan officers with dedicated expertise in VA, jumbo, and renovation financing.
Digital Application Tools: Online application process available for borrowers who prefer self-service.
Best For
Borrowers with specialty financing needs, particularly veterans exploring VA loan eligibility, jumbo buyers, or those considering renovation financing, who are ready to move into a full, verified preapproval process.
How These Options Compare at a Glance
| Feature | FreePreQuals.com (NoTouch Credit Pull) | Typical National Lender (e.g., Rocket) | Typical Bank / Branch Lender | Regional Lender (e.g., Alcova) |
|---|---|---|---|---|
| Credit Pull Type | Soft pull only | Hard pull | Hard pull | Hard pull |
| Credit Score Impact | Zero | 5–10 points (CFPB) | 5–10 points (CFPB) | 5–10 points (CFPB) |
| Pre-Qualification Letter | Yes, real letter included | Preapproval letter (hard pull required) | Preapproval letter (hard pull required) | Preapproval letter (hard pull required) |
| Cost to Borrower | Free | No upfront fee | No upfront fee | No upfront fee |
| Broker vs. Lender | Broker (500+ wholesale lenders) | Direct lender (single product set) | Bank / direct lender | Direct lender |
| Loan Programs | FHA, VA, USDA, Conventional, Jumbo | Varies by lender | Varies by bank | FHA, VA, Conventional, others |
| Report Duration (Hard Pull) | N/A | 2 years on credit report | 2 years on credit report | 2 years on credit report |
Can You Get a Mortgage Pre-Approval With a Soft Pull?
This is the most common question buyers ask, and the honest answer has two parts. A fully underwritten preapproval, the kind sellers want to see attached to an offer, generally requires a hard credit inquiry so the lender can verify your full credit file. A soft pull mortgage pre-approval style first step, on the other hand, is possible through a soft pull mortgage pre-qualification. It gives you a real, usable estimate of your budget with no hard inquiry and no credit score impact.
That is exactly what the NoTouch Credit Pull at FreePreQuals.com delivers. It is a mortgage pre-approval soft pull alternative for the exploration phase: you see what you can likely qualify for, receive a pre-qualification letter, and keep your score intact until you have a home under contract.
Worked Example: What the Wrong Pull Can Cost
Take a $300,000, 30-year loan. At 6.50%, the principal and interest payment is about $1,896 per month. If an unnecessary hard inquiry nudges a borrower into a pricing tier that adds 0.25%, the rate becomes 6.75% and the payment rises to about $1,946 per month. That is roughly $50 more each month, or about $17,850 over 30 years. These figures are illustrative only, and your actual rate depends on your full profile. The Consumer Financial Protection Bureau explains how mortgage inquiries are counted and how rate shopping is treated.
The Practical Sequence
Start with a no hard inquiry mortgage pre-qualification to set your budget and price range. Move to a full preapproval with a hard pull only when you are ready to make an offer. Buyers in Virginia, Florida, Tennessee, and Georgia can begin with a free soft pull pre-qualification from Duane Buziak, NMLS #1110647, a licensed broker with Coast2Coast Mortgage LLC, NMLS #376205.
This section is for informational purposes only and is not a commitment to lend. Rates and eligibility vary and all loans are subject to credit approval and underwriting.
Frequently Asked Questions
Q: What is the difference between prequalification and preapproval?
Prequalification is an estimate of what you may qualify for, typically based on self-reported information and a soft credit pull. Preapproval is a verified commitment from a lender, based on documented income, assets, and a hard credit inquiry. Preapproval carries more weight with sellers but costs you a credit score impact.
Q: Does getting prequalified hurt your credit score?
It depends on the lender. Most lenders run a hard pull even for prequalification, which can reduce your score by 5–10 points. FreePreQuals.com uses a NoTouch Credit Pull, a soft pull only, so there is zero credit score impact.
Q: What is a NoTouch Credit Pull?
The NoTouch Credit Pull is the proprietary soft pull pre-qualification process used by Duane Buziak at FreePreQuals.com. It pulls only soft inquiry data, generates a real pre-qualification letter, and leaves your credit score completely untouched.
Q: Is a prequalification letter good enough to make an offer on a home?
In many markets, sellers prefer a full preapproval letter. However, a prequalification letter is useful for early-stage shopping, understanding your budget, and working with a buyer’s agent. When you’re ready to write an offer, converting to a full preapproval is the recommended next step.
Q: How long does a hard inquiry stay on my credit report?
According to the CFPB, hard inquiries remain on your credit report for two years. Their scoring impact typically diminishes over time, but they are visible to any lender who pulls your report during that window.
Q: Can I get prequalified multiple times without hurting my credit?
If you use a soft pull pre-qualification service like FreePreQuals.com, yes. Soft pulls do not affect your score regardless of how many times they are run. Hard pulls, however, compound if you apply with multiple lenders outside of a rate-shopping window.
Q: What is the 2026 conforming loan limit?
The 2026 conforming loan limit is $806,500 for standard areas and $1,249,125 for designated high-cost areas. Loans above these limits are classified as jumbo loans and follow different qualification criteria.
Q: How do I get a free mortgage pre-qualification without a hard pull?
Visit FreePreQuals.com and complete the free pre-qualification form. Duane Buziak will run a NoTouch Credit Pull, a soft pull only, and issue a real pre-qualification letter at no cost. No hard inquiry, no credit score impact, no obligation.
Which Option Is Right for You
The sequencing matters more than the choice itself. If you haven’t found a home yet, there is no strategic reason to absorb a hard pull. Start with a no credit impact mortgage pre-qual to understand your budget, establish your price range, and begin working with a buyer’s agent, all without touching your credit score.
When you’ve found a home and are ready to write an offer, that’s the moment to convert to a full preapproval. At that stage, the hard pull is justified because you’re moving toward a real transaction, not just exploring.
The recommended sequence: complete your NoTouch Credit Pull pre-qualification at FreePreQuals.com first. Use it to shop, compare programs, and get comfortable with your numbers. Then, when you’re under contract or close to it, move to a verified preapproval with the lender whose program fits your file best. This sequence protects your score, keeps your options open, and costs you nothing upfront.
For buyers in Virginia, the state’s median home prices have been tracked by Virginia Housing, and first-time buyer activity in the state continues to be strong. Given that most Virginia homes are priced within the 2026 conforming limit of $806,500, the majority of buyers in the state qualify for conventional or government-backed loan programs, making a soft pull pre-qualification an especially practical first step before committing to any lender.
Duane Buziak (NMLS #1110647) offers free soft pull mortgage pre-qualification for buyers in Virginia, Florida, Tennessee, Georgia, and Washington DC. If you’re ready to find out what you qualify for without risking your credit score, get your free mortgage prequalification today. Or call directly: 804-212-8663.
Disclaimer: This article is for informational purposes only and does not constitute financial or legal advice. Loan programs, rates, and eligibility requirements are subject to change. Duane Buziak, NMLS #1110647, is a licensed mortgage broker operating under Coast2Coast Mortgage LLC, NMLS #376205. Licensed in Virginia, Florida, Tennessee, Georgia, and Washington DC. Not licensed in all states. This is not a commitment to lend. All loans subject to credit approval, underwriting review, and applicable guidelines.
Duane Buziak, NMLS #1110647
Mortgage Maestro | Coast2Coast Mortgage LLC, NMLS #376205
Licensed: Virginia, Florida, Tennessee, Georgia, Washington DC
Phone: 804-212-8663
FreePreQuals.com